The email comes from a customer’s procurement team, not its sustainability department. Attached is a spreadsheet with tabs for electricity use, fuel, waste, workforce numbers and company policies. There is a polite note saying the information is needed for the customer’s annual sustainability reporting, and a deadline two weeks away.
Many SME owners treat this as paperwork and hand it to whoever has time. That is a mistake. A supplier ESG questionnaire is really a test of whether your business can produce believable numbers about itself. Suppliers that answer clearly, on time and with evidence look easier to work with. Suppliers that guess, leave blanks or send a glossy brochure instead of data look like a risk.
Why these requests are arriving now
In Malaysia, the pressure comes mainly from the National Sustainability Reporting Framework, launched in September 2024. It phases in sustainability reporting based on the ISSB standards. Large Main Market listed companies started in 2025, the remaining Main Market companies followed in 2026, and ACE Market companies and large non-listed companies with annual revenue of RM2 billion and above come in from 2027.
The important point for suppliers is that these companies will eventually have to report emissions across their value chain, not just their own operations. That information has to come from somewhere, and much of it comes from SME suppliers. Bursa Malaysia has also introduced a platform to help listed companies make supplier engagement and data collection more structured. Multinational buyers and export customers apply similar pressure through their own supplier codes.
SMEs themselves are not required to produce a full ISSB-aligned sustainability report. But “not mandatory” does not mean “not expected”. If a major customer needs your data to complete its own report, your ability to provide it becomes part of how you are assessed as a supplier.
What customers are actually asking for
Questionnaires vary, but most first-round requests ask for a similar set of basic information. The table below shows what each item usually means, where the data sits in a typical SME, and where it tends to go wrong.
| Typical request | What it feeds | Where the data usually lives | Common gap |
|---|---|---|---|
| Electricity consumption (kWh) | Scope 2 emissions | Utility bills for each premises | Bills for a warehouse, branch or shared premises are missing or paid by a landlord |
| Fuel use (diesel, petrol, LPG, natural gas) | Scope 1 emissions | Fuel cards, petty cash claims, generator and forklift logs | Fuel bought with cash is recorded in ringgit, not litres |
| Waste generated and how it is handled | Environmental disclosures | Contractor invoices and waste consignment records | Volumes are estimated rather than recorded |
| Headcount, turnover and workplace injuries | Social disclosures | Payroll and HR records, accident logs | Contract and agency workers are left out |
| Written policies (anti-bribery, code of conduct, data privacy) | Governance disclosures | Staff handbook, director decisions | Practices exist informally but nothing is written or approved |
| Emissions intensity (for example, per unit of revenue) | Comparison across suppliers | Emissions figures plus financial accounts | Energy data covers a calendar year while revenue covers a different financial year |
Notice that almost none of this requires new technology. Most of it already exists in invoices, payroll and accounts. The hard part is collecting it consistently, for a defined period and a defined set of premises, and keeping the evidence.
The Supplier ESG Readiness Ladder
It helps to think of ESG readiness as a ladder rather than a single pass-or-fail test. Each level builds on the one below it.
- Level 0: Reactive. Nothing is collected until a customer asks. Answers are assembled under deadline pressure, often by guessing.
- Level 1: Recorded. Twelve months of electricity bills, fuel records, headcount and waste invoices are gathered in one place, for every site the business operates.
- Level 2: Calculated. Scope 1 and Scope 2 emissions are calculated using a recognised, documented method, and the boundary (which sites, vehicles and entities are included) is written down.
- Level 3: Managed. One named person owns the data. Figures are updated monthly or quarterly, and the business has at least one improvement target.
- Level 4: Evidenced. Every figure can be traced to a source document. The calculation has been reviewed by someone other than the person who prepared it, and the business could answer follow-up questions from a customer’s sustainability team without scrambling.
Most first-time requests only need Levels 1 and 2 done properly. Moving from Level 0 to Level 2 is usually the biggest single improvement in how a supplier is perceived.
Start with the free frameworks before buying software
Malaysian SMEs do not need to design their own disclosure list. Capital Markets Malaysia, an affiliate of the Securities Commission, publishes the Simplified ESG Disclosure Guide (SEDG) for SMEs in supply chains. It is aligned with the ASEAN Simplified ESG Disclosure Guide, a voluntary regional guide whose second version groups 38 disclosures across 15 topics into Basic, Intermediate and Advanced levels.
That tiered structure is useful for planning. Start with the Basic disclosures that match what customers are asking for, and move up only when you have the data and the need.
For emissions, Capital Markets Malaysia also offers a free SEDG GHG Emissions Calculator for Scope 1 and Scope 2. It works on a simple principle: activity data multiplied by an emission factor. You enter fuel and electricity quantities, and it applies standard factors, including grid factors for Peninsular Malaysia, Sabah and Sarawak. The results are estimates based on a disclosed method. That is what most customers need at this stage, but describe them as estimates, not exact measurements.
Scope 3, the emissions from your own suppliers and wider value chain, is more complex. Most customers do not expect a small supplier to report it in the first round. Get Scope 1 and 2 right first.
A 90-day plan for SME suppliers
Days 1–30: Assign, define and collect
- Name one person responsible for ESG data. In most SMEs this sits well with finance or operations, not marketing.
- List every site, vehicle, generator and entity the business controls, and decide what is inside your reporting boundary.
- Collect the last twelve months of electricity bills, fuel records, waste invoices and headcount figures into one shared folder.
- Choose a reporting period, ideally matching your financial year so intensity figures line up.
Days 31–60: Calculate and document
- Convert fuel spending into litres or kilograms where needed, and record how you did it.
- Run Scope 1 and Scope 2 figures through a recognised calculator and save the output.
- Write down, or formally approve, the basic governance policies customers commonly ask for, such as anti-bribery, code of conduct and data protection.
- Check the figures against your own accounts and sales records so the same number does not appear in three different versions.
Days 61–90: Package and improve
- Prepare a one-page ESG fact sheet with your boundary, period, key figures, method and a contact person.
- Keep a source-document folder behind every number on that page.
- Set one realistic improvement target, such as electricity use per unit produced, and decide how you will track it.
- Ask someone outside the data owner’s team to review the calculation before it goes to a customer.
A fact sheet like this turns every future questionnaire from a two-week scramble into a two-hour update. It can also go into tender submissions and customer onboarding packs.
The green claim test: do not turn data into slogans
Once SMEs start measuring, there is a temptation to put the results into marketing straight away: “eco-friendly”, “green supplier”, “carbon neutral”. Broad claims like these are hard to support, and a customer’s sustainability team will notice. Before any environmental claim goes on a website, brochure or tender document, ask these questions:
- Is it specific? Does it name the activity, site or product, rather than the whole company?
- Is there a baseline? Does it compare against a stated earlier period?
- Is the boundary clear? Does it say what is included and what is not?
- Is there evidence? Could you hand over the source documents tomorrow?
- Is it current? Is it still true today, or did it describe a single year?
- Would it survive a follow-up question? If a customer asked “how did you calculate that?”, would the answer strengthen the claim or weaken it?
A claim such as “we reduced electricity use per unit produced at our main plant compared with the previous financial year, based on utility bills and production records” is less exciting than “green manufacturer”. It is also far more credible.
Disclosure, certification, awards and records are different things
As ESG data improves, some SMEs start asking how to get their progress recognised. It is worth being clear about what each route actually does.
| Route | What it shows | Who decides |
|---|---|---|
| ESG disclosure | What your data is, using a recognised format | You prepare it; customers and financiers use it |
| Management system certification (for example, ISO 14001) | That defined processes are in place and audited | An accredited certification body |
| Business awards | That judges preferred your entry within a field | A judging panel, using criteria that vary widely |
| Record recognition | That a clearly defined, measurable achievement was verified | The record body, assessing evidence against the claim |
None of these replaces the others. Record recognition, in particular, does not replace regulatory compliance, environmental approvals, audited sustainability reporting or accredited certification. A good questionnaire answer is still a good questionnaire answer, with or without any title attached.
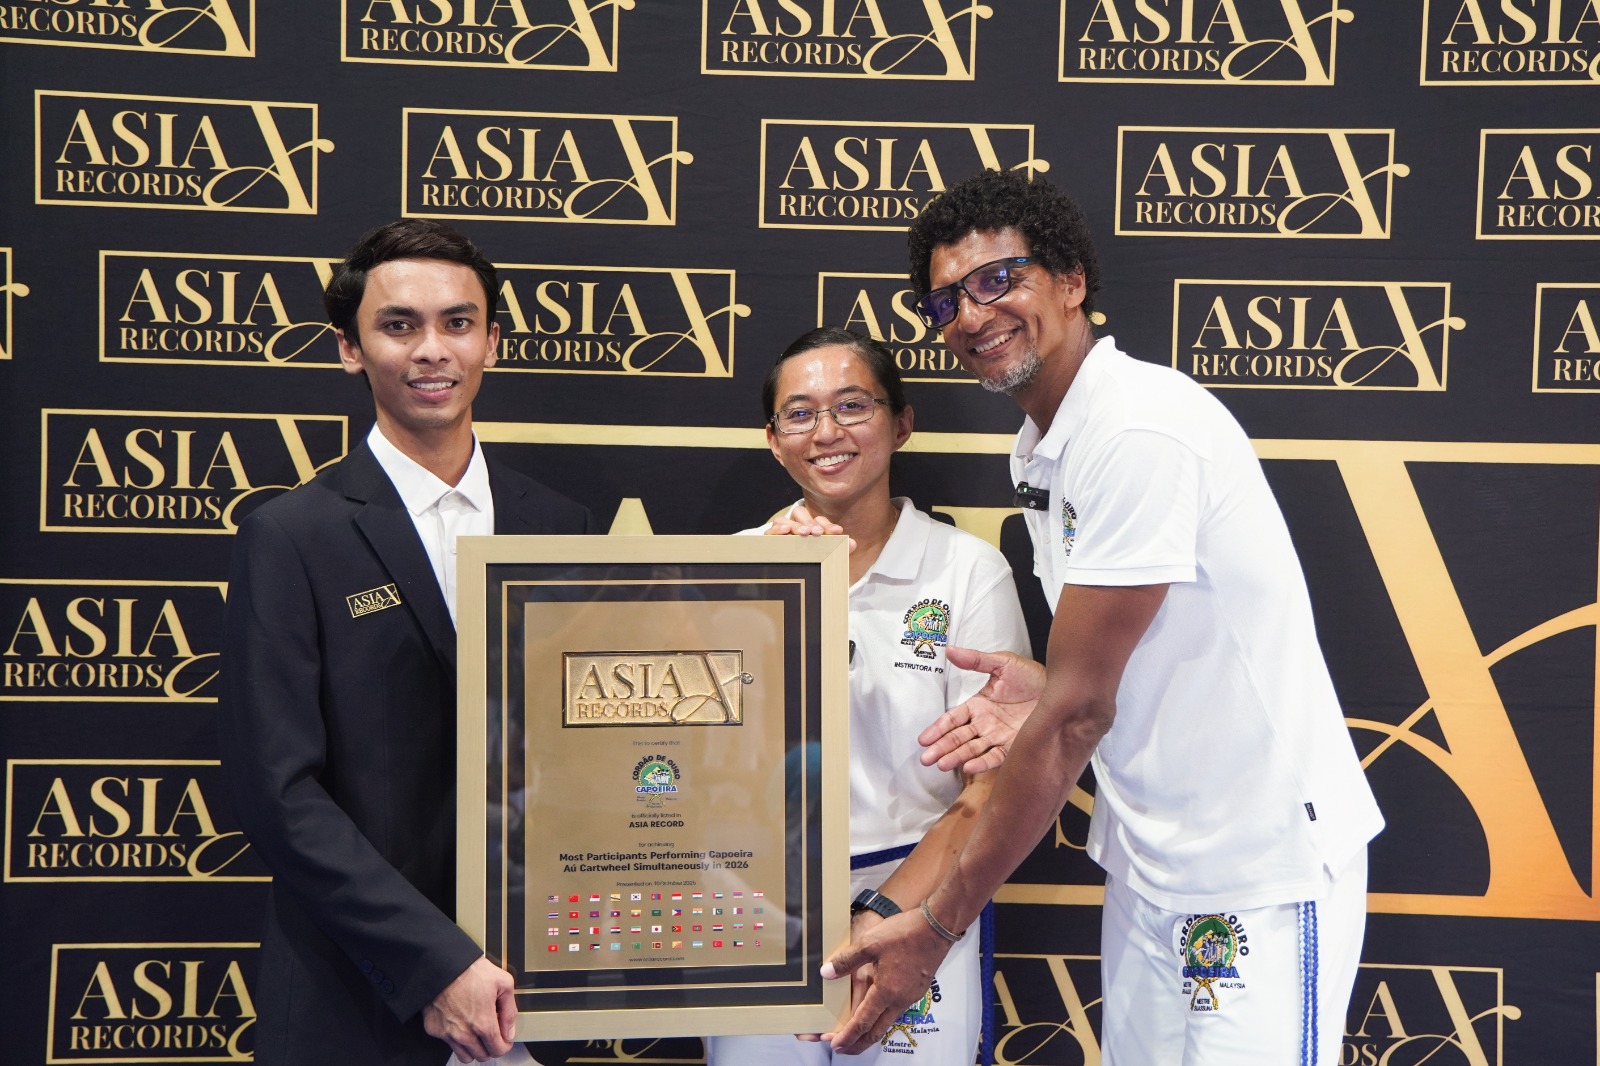
There are cases, however, where an environmental or operational result goes well beyond normal progress and is clearly measured. Examples might be an exceptional verified volume of material recovered, or a defined milestone achieved over a set period. For milestones like these, formal recognition can add independent weight. Asia Record documents measurable achievements by individuals, businesses and organisations across Asia. It assesses a proposal by comparing a clearly defined claim with supporting evidence and the conditions under which it was measured, a process explained on its page on how record recognition in Asia is assessed.
The discipline is the same as good ESG reporting: define the claim exactly, fix the measurement conditions and keep the original records. For SMEs wondering how to get an Asia Record for a sustainability or operational milestone, the starting point is that evidence trail, not the announcement. Businesses with a qualifying, well-documented achievement can review the Asia Record application steps to see what a complete submission involves.
What good readiness actually buys you
The direct benefit is simple. You answer customer requests faster, with fewer follow-up questions, and you look like a lower-risk supplier when procurement teams compare vendors. The indirect benefits are often bigger. Once electricity and fuel use are tracked monthly, waste and inefficiency become visible. Written governance policies make tender submissions easier. And a business that can back every number with a document is better placed for financing conversations, larger contracts and any form of recognition it may pursue later.
ESG requests are not going away. The SMEs that treat the first questionnaire as the start of a simple, repeatable system will spend less time on the second, and will be in a stronger position when the questions get harder.