
A restaurant runs a weekday promotion and the kitchen has its busiest month of the year. A distributor accepts a large order at a sharp discount and the warehouse works overtime to fill it. A manufacturer joins an online marketplace and unit sales double within a quarter. In each case, the business is visibly bigger. In each case, the owner may also have less money left at the end of the month than before.
The gap between those two outcomes usually sits in a number many SMEs never calculate by product, channel or customer: contribution margin. Revenue tells you how much came in. Contribution margin tells you how much of each sale stays in the business to pay for everything else.
What Contribution Margin Actually Tells You
Contribution margin is the selling price of a product or service minus the costs that rise and fall with each sale. These variable costs typically include ingredients or materials, packaging, sales commissions, marketplace or delivery platform fees, payment processing charges, delivery costs and piece-rate labour. Rent, salaried staff, loan repayments and software subscriptions are usually fixed. They stay roughly the same whether you sell 500 units this month or 600.
Whatever is left after variable costs “contributes” to covering those fixed costs. Once fixed costs are covered, the remaining contribution becomes profit. That makes it the most useful number for everyday decisions: if we sell one more unit, at this price, through this channel, how much better off are we?
It is not the same as the gross margin on your financial statements. Gross margin often includes some fixed production costs and leaves out selling costs such as platform commissions. Both have their place. For decisions about pricing, promotions and channels, contribution is the cleaner question.
The same logic sits behind how productivity is measured nationally. Malaysia’s Department of Statistics measures MSME labour productivity as value added per person employed, which reached RM85,299 in 2025. That is a measure of what remains after inputs, not of gross turnover. Your own products deserve the same treatment.
:antCitation[]{citations=”c1044def-5182-4710-9f4d-5e017131be58″}
The Same Product Can Earn Very Different Amounts
Consider a single signature dish sold three ways by a restaurant. The figures below are illustrative assumptions, not industry benchmarks. Replace them with your own.
| Item | Dine-in, full price | Delivery platform | Dine-in, 20% weekday discount |
|---|---|---|---|
| Selling price | RM14.00 | RM16.00 | RM11.20 |
| Ingredients | RM4.50 | RM4.50 | RM4.50 |
| Packaging | RM0.00 | RM1.20 | RM0.00 |
| Platform commission (assumed 30%) | RM0.00 | RM4.80 | RM0.00 |
| Payment fee (assumed 1%) | RM0.14 | Included in commission | RM0.11 |
| Contribution per plate | RM9.36 | RM5.50 | RM6.59 |
| Contribution margin ratio | 66.9% | 34.4% | 58.8% |
The delivery plate brings in more revenue than the dine-in plate, yet it contributes about 41% less. To earn the contribution of 100 dine-in plates, the restaurant needs to sell around 171 delivery plates. An owner who judges channels by revenue or order count would see delivery as the stronger performer. An owner who looks at contribution would see a channel that needs either a higher price, a smaller packaging cost or a clear role in reaching new customers.
How Much Extra Volume a Discount Needs
Before approving any promotion, run one simple formula:
Extra volume needed = (original contribution per unit ÷ discounted contribution per unit) − 1
In the example above, RM9.36 ÷ RM6.59 − 1 = 0.42. The weekday promotion must sell 42% more plates simply to earn the same contribution as before. Anything less, and the busier kitchen is earning less money. This also leaves out the extra staff hours, wastage and wear that higher volume usually brings. The lower a product’s margin to begin with, the steeper this hurdle becomes.
The Volume-Contribution Matrix
Once you have contribution per unit for your main products, services or channels, sort them by two questions: do they sell in volume, and does each sale contribute strongly? Each combination calls for a different response.
| Position | What it looks like | Main risk | Practical response |
|---|---|---|---|
| Core earners High volume, strong contribution |
Signature products, loyal repeat lines | Complacency on quality, stock-outs, unnecessary discounting | Protect availability and consistency; resist discounting what already sells |
| Busy but thin High volume, weak contribution |
Heavily promoted items, low-priced wholesale accounts, high-commission channels | Staff and capacity consumed for little return | Reprice, redesign the bundle, renegotiate channel terms, set minimum order sizes |
| Quiet earners Low volume, strong contribution |
Premium options, add-ons, specialised services | Under-promoted and under-stocked | Test better visibility or staff recommendations without cutting price |
| Review list Low volume, weak contribution |
Legacy SKUs, rarely ordered menu items | Inventory, complexity and wastage | Simplify, merge or retire unless there is a clear strategic reason to keep |
Some “busy but thin” items are deliberate: a traffic-building product that brings in customers who then buy higher-contribution items. That is a legitimate strategy, but only if you measure it. Check whether customers who buy the promoted item actually add other purchases. If they do not, the promotion is subsidising itself.
Five Numbers to Produce for Every Major Product, Channel or Customer
- Realised selling price. What you actually received after discounts, vouchers, rebates and free items, not the list price.
- Direct material or ingredient cost, including wastage. Cost per unit sold, not per unit made.
- Channel costs. Commissions, marketplace fees, delivery charges, packaging specific to that channel and sales incentives.
- Payment and credit costs. Card and e-wallet fees, plus the cost of waiting for payment on credit sales.
- Units sold over a defined period. Drawn from one agreed system so the volume number is not disputed.
The fourth point matters more than many owners expect. A high-contribution wholesale account that pays in 120 days can still strain the business, which is why contribution analysis should sit alongside an understanding of the cash conversion cycle. The fifth point is where many SMEs stumble. If sales, finance and operations each hold a different unit count, it is worth fixing that first with basic data governance.
Common Mistakes When SMEs First Calculate Contribution
- Using list prices. If sales staff routinely give 5% off to close deals, your real contribution is lower than the spreadsheet says.
- Ignoring wastage, rejects and rework. For manufacturers, a unit that has to be scrapped still consumed material. Contribution should be calculated on good output, a point covered in more detail in our guide to measuring production yield.
- Averaging across channels. A single business-wide margin hides the fact that one channel may be carrying another.
- Loading fixed costs onto each unit. Dividing rent across every product can make a perfectly useful item look unprofitable. Cutting it then leaves the same rent spread over fewer sales.
- Calculating once and forgetting. Supplier prices, platform terms and sales mix all move. A quarterly review is a reasonable minimum, and any major price change should trigger an immediate recalculation.
When Volume Itself Is the Achievement
None of this means volume is unimportant. Sustained high volume can reflect genuine customer demand, reliable operations and a strong reputation built over years. Some volume milestones are significant enough to stand as achievements in their own right.
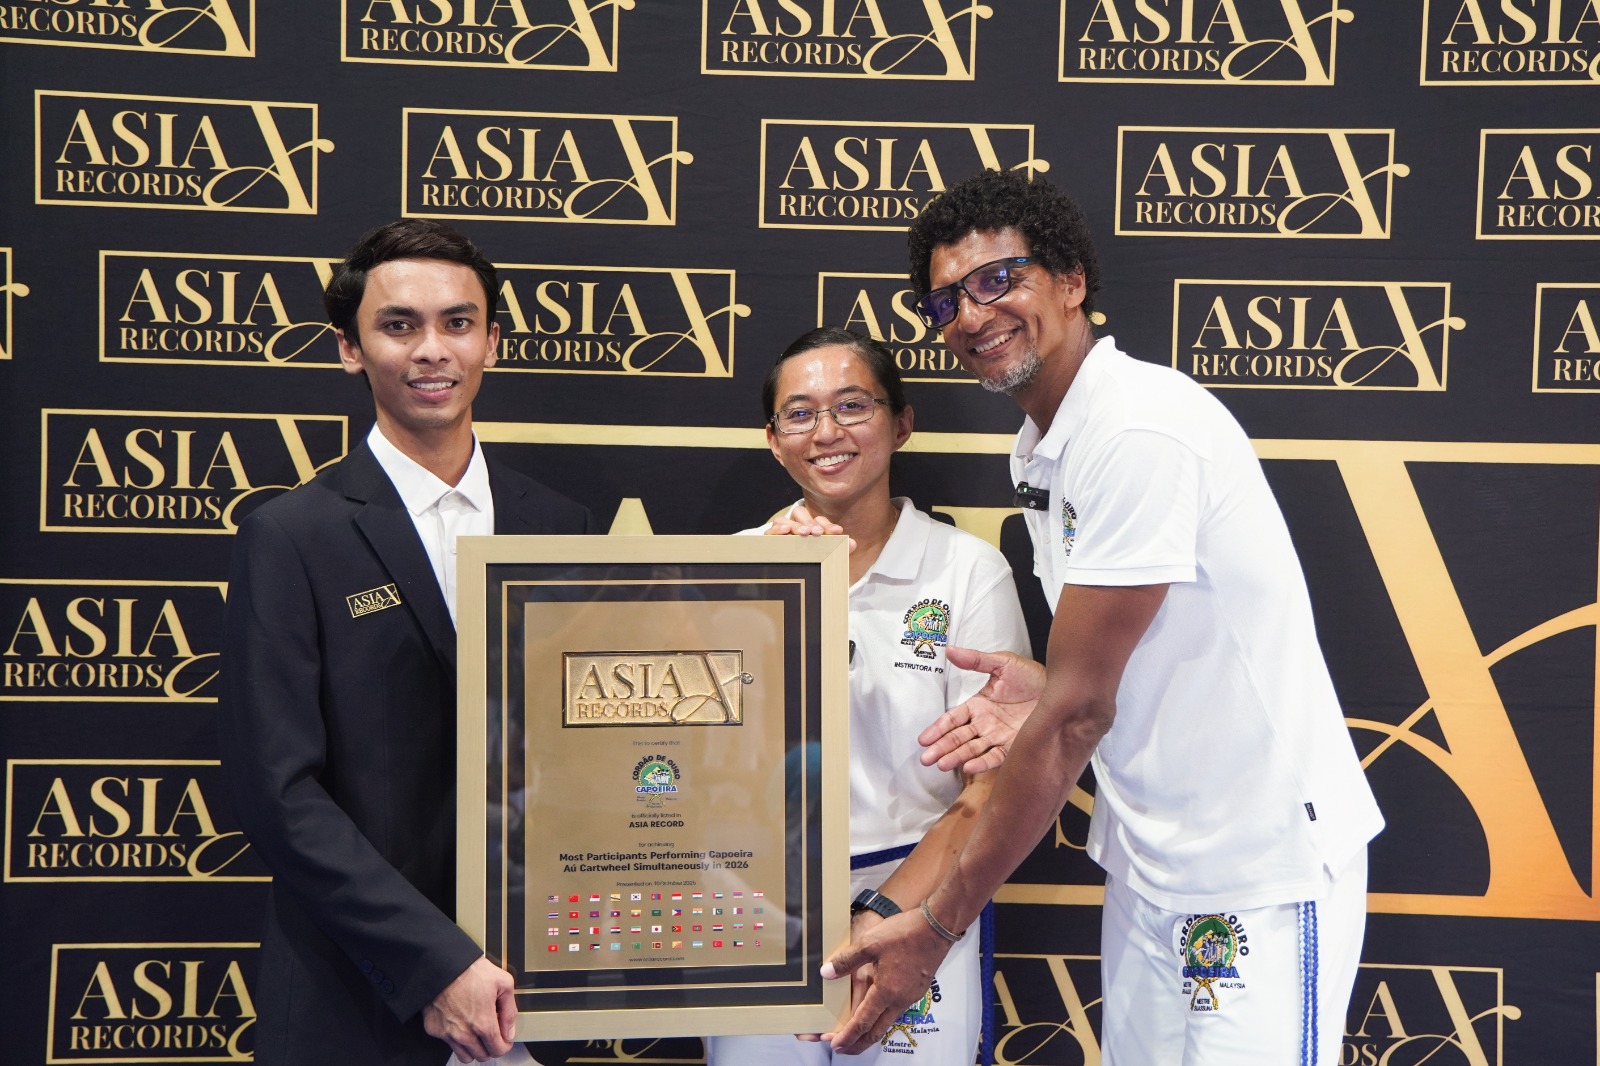
Pan Heong Restoran in Batu Caves, Selangor, is one example. The restaurant, established in 1988, was presented with an Asia Record title in September 2026 for the most Wat Tan Hor sold by a single restaurant outlet in 2025. Note how tightly the achievement is defined: one dish, one outlet, one calendar year. It recognises how much was sold. It does not claim anything about margin, and it does not need to.
That is the useful lesson for any SME. Keep two questions separate. “How much did we sell?” can be a measurable, verifiable achievement worth communicating. “How much did each sale earn?” is a management question that decides whether pushing for more volume is wise. Mixing the two leads either to overclaiming in marketing or to chasing volume that quietly drains the business.
For SMEs considering an Asia record application for a sales or production volume milestone, the same discipline applies. The Asia record certification process asks applicants to state exactly what is being claimed and by whom, and to set measurement conditions such as dates, locations and units. The result must then be supported with evidence such as documents and measurement records. Anyone asking how to get an Asia Record for a business milestone will find that the hard part is rarely the number itself. It is showing clearly how the number was counted.
Conveniently, the point-of-sale data by item, outlet and date that supports a contribution review is the same data that supports a credible volume claim. It is also worth being precise about scope. Record recognition for a volume achievement is a statement about what was achieved. It is not an assessment of profitability, product quality, food safety or regulatory compliance, which are governed by their own licences and standards.
A 30-Day Contribution Review
You do not need new software to start. A spreadsheet and your existing sales records are enough.
- Week 1: List your top 10 to 20 products, services or customer accounts by revenue. Pull realised prices for the last three months, not list prices.
- Week 2: Attach variable costs to each, split by channel where the costs differ. Note any figures you are estimating, and who will confirm them.
- Week 3: Calculate contribution per unit and the contribution margin ratio. Place each item in the volume-contribution matrix and flag every “busy but thin” item.
- Week 4: Decide one action for each flagged item, such as a price change, a channel adjustment, a minimum order or a bundle redesign. Set a date to measure the result.
Growth worth having is growth where each additional sale leaves the business stronger. Once you know what each product, channel and promotion actually contributes, decisions about discounts, delivery platforms and big orders stop being guesses. Volume can then become something to be proud of, not something to worry about.