Your SME finishes the quarter 28% ahead of the same period last year. Sales celebrates. Management starts discussing another salesperson, additional stock and perhaps a larger premises.
Then someone asks a less comfortable question: where did the extra revenue actually come from?
If most of the increase came from one unusually large order, a temporary promotion or a customer that may not buy again, the business has still achieved higher sales. What it has not necessarily built is a stronger revenue base.
This is the difference between revenue growth and revenue quality.
For an SME, revenue quality is a management view of how dependable, repeatable and economically useful its sales are. It does not replace formal accounting rules, and it is not a single accounting ratio. It is a way of examining the composition behind the top line before management makes decisions based on it.
RM1 Million of Revenue Can Tell Several Different Stories
Consider four businesses that each generated the same amount of sales during a period.
| Business | Where the Revenue Came From | Management Question |
|---|---|---|
| A | Hundreds of customers making regular repeat purchases | Are retention and margins holding as volume grows? |
| B | One unusually large contract | Will that contract repeat, and what happens when it ends? |
| C | A major promotional campaign with deep discounts | How much demand remains at normal pricing? |
| D | Existing contracts plus a growing group of repeat customers | Can operations continue serving the base reliably? |
The accounting revenue may be equally real in all four examples. The management implications are completely different.
An owner who looks only at total sales may treat every ringgit of growth as equally durable. That can lead to permanent decisions—new employees, equipment leases, larger inventory commitments or additional premises—being funded by revenue that was temporary.
The Six-Part SME Revenue Quality Test
A useful review does not need sophisticated software. Start by examining six dimensions of the revenue you already report.
1. Repeatability
Ask how much of the current period’s revenue comes from customers or commercial arrangements that have a realistic path to another purchase.
That does not mean every SME needs subscriptions. A maintenance contractor may have annual renewals. A distributor may have customers ordering every month. A commercial kitchen supplier may have irregular orders from the same restaurant groups. A professional-services company may win repeat projects rather than contractual recurring revenue.
The relevant question is not, “Is this subscription revenue?” It is, “What evidence suggests this customer or revenue stream will continue?”
This is closely related to customer retention, but it is not identical. An SME can retain many customers while their spending falls. It can also grow because new customers compensate for shrinking existing accounts.
That is why management should compare revenue composition with its existing customer retention analysis.
2. Concentration
A growing top line can become less resilient when increasingly large portions come from one customer, product, marketplace, country or sales channel.
Suppose revenue increases from RM4 million to RM5 million because one customer adds RM1 million of new business. That is genuine growth. But the SME has also become more dependent on that relationship.
Do not subtract concentrated revenue from the sales figure. Instead, label the dependency clearly.
Management should be able to identify its largest customer, top three customers, major product lines and important channels and see how their shares have changed. The existing Asia SME guide to customer concentration risk can then be used to stress-test the largest exposures.
3. Margin Quality
Revenue growth is much less useful when the additional sales carry poor economics.
A new contract can increase turnover while requiring unusually low pricing, expensive overtime, expedited freight, extra support, custom development or sales commissions that leave little contribution behind.
Separate sales growth from gross margin or contribution margin. If revenue is rising substantially faster than the economic value retained from those sales, investigate why.
This is particularly important during aggressive expansion. A company can appear larger while becoming harder to fund.
4. Cash Conversion
A sale and cash in the bank are not the same event.
Growth that requires the SME to fund raw materials, payroll and operating costs long before customers pay can create substantial working-capital pressure.
For each important revenue stream, ask:
- When does the business spend cash to fulfil the work?
- When can it invoice?
- How long does the customer normally take to pay?
- Are receivables becoming older as sales increase?
- Does the business need more stock or work in progress to support the growth?
A strong order book may therefore be good news and a cash challenge at the same time. Management should review the result alongside the company’s cash conversion cycle.
5. Normality
Separate what happened under normal trading conditions from what happened because of an unusual event.
Examples include:
- a one-time government or corporate project;
- a major product launch;
- a temporary shortage affecting competitors;
- a festive-season spike;
- clearance of old inventory;
- a large event or exhibition order;
- a founder personally closing an exceptional deal;
- a deep promotional campaign; or
- a single export shipment unusually large for the business.
None of these sales should automatically be dismissed. One-off business can be highly profitable and strategically valuable.
The mistake is treating exceptional revenue as the new normal without evidence.
6. Evidence
The final test is whether management can reproduce the number from reliable business records.
If the owner says sales grew 40%, can finance explain exactly which invoices, customers, products and periods created the increase?
Can the company separate cancelled transactions, refunds, returns and credit notes where relevant? Can the result be reconciled with the accounting records? Are management reports using the same definition from one period to the next?
The more important a growth claim becomes, the more important this discipline is.
Build a Revenue Quality Bridge
One useful monthly exercise is to turn total revenue growth into a bridge showing what caused the change.
| Growth Component | Question to Ask |
|---|---|
| Existing-customer growth | Are established customers genuinely buying more? |
| New repeatable customers | Are newly acquired customers beginning a pattern likely to continue? |
| Contracted revenue | What portion is supported by current enforceable commercial arrangements? |
| Price effect | How much growth came from higher prices rather than greater volume? |
| One-off projects | Which sales have no reasonable expectation of repeating? |
| Promotional effect | How much volume depended on discounts or temporary campaigns? |
| Lost or shrinking customers | What deterioration is being hidden by new sales? |
This turns “revenue increased” into something management can actually use.
Imagine an SME reports a RM600,000 year-on-year increase. The bridge might reveal that RM250,000 came from existing customers buying more, RM180,000 came from new customers that have already reordered, RM300,000 came from a one-time project and RM130,000 was lost when several older customers reduced their spending.
Total growth is still RM600,000. But management now understands the forces underneath it.
Use Three Revenue Buckets for Planning
For planning purposes, SMEs can classify revenue into three simple buckets.
Core Revenue
Revenue supported by an established pattern, active contracts, repeat purchasing or another strong basis for expecting continued business.
Developing Revenue
New customers, products or channels showing encouraging early results but without enough history to treat them as dependable.
Exceptional Revenue
Large projects, unusual orders, seasonal peaks or other sales that should not automatically be carried forward into next year’s baseline.
This classification is not an accounting treatment. It is an internal decision tool.
It can make budgeting more disciplined. Permanent expenses should not automatically be added simply because exceptional revenue had an excellent quarter.
Watch for Five Signs That Headline Growth Is Misleading Management
- Sales are rising but repeat business is weakening. New acquisition may be masking customer loss.
- Revenue is rising but gross margin is falling sharply. Growth may be coming from low-quality contracts or excessive discounting.
- Sales are rising but receivables are growing faster. The SME may be financing customers rather than converting growth into cash.
- One account explains most of the improvement. Growth and concentration risk have arrived together.
- The forecast simply annualises the best recent month. Seasonal or exceptional performance may have been mistaken for the new baseline.
These indicators belong beside revenue on an SME KPI dashboard. The purpose is not to create more reporting. It is to stop one impressive number from hiding the questions management actually needs to answer.
When Revenue Growth Becomes a Business Achievement
There is also an important distinction between durable business performance and a measurable exceptional achievement.
An SME might achieve an unusually high sales volume, transaction count, export milestone or another clearly defined commercial result during a particular period. That achievement can be significant even if management would not assume the same result will recur indefinitely.
This is where measurement discipline becomes valuable beyond internal management.
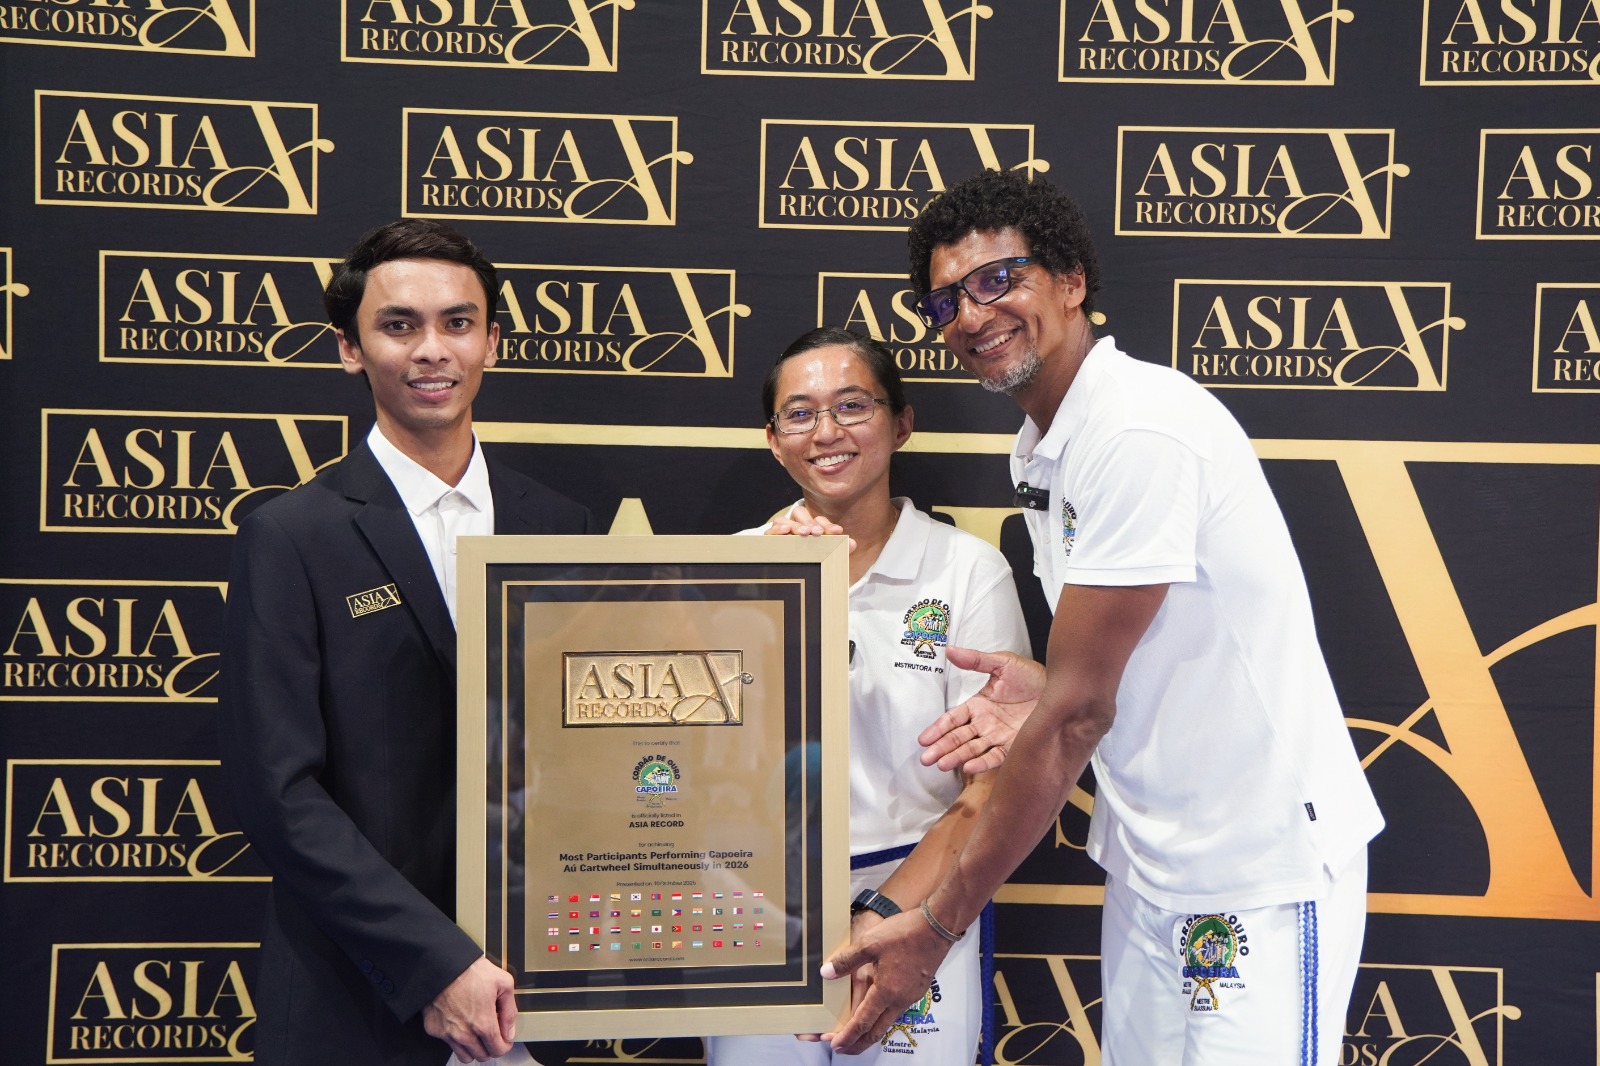
Asia Record documents measurable achievements by businesses, organisations and individuals across Asia. Its official application process asks applicants to define the achievement and provide supporting evidence showing what was achieved, how it was measured and the conditions surrounding it.
An SME with an exceptional and verifiable milestone can review the official Asia Record application information when considering business achievement recognition in Asia.
For companies researching how to get an Asia Record, the important starting point is not a promotional description such as “fast-growing SME”. It is a precise claim supported by records that another party can examine.
The distinction should remain clear. Becoming an Asia Record holder for a defined business record in Asia documents that particular achievement. It does not automatically establish that the business is profitable, financially stable, well governed or likely to repeat the result. Record recognition also does not replace regulatory approval, professional accreditation or industry certification.
A Monthly Revenue Quality Review for SMEs
Management can run the following review without creating another complicated reporting system.
- Reconcile total revenue. Start with a figure finance considers reliable.
- Separate existing and new customers. Identify which group actually produced the growth.
- Flag one-off and unusual sales. Do not remove them; label them.
- Measure concentration. Check the largest customers, products and channels.
- Compare margin. Determine whether incremental sales produced acceptable economics.
- Check collections. See whether increased revenue is turning into cash.
- Identify repeatability. Decide what evidence supports carrying each major revenue stream into the forecast.
- Record exceptional milestones separately. Preserve the underlying evidence when an unusual result may have independent significance.
After several months, management gains something much more useful than a sales chart: a history showing which parts of growth stayed, which disappeared and why.
Growth Is Stronger When You Know What Is Underneath It
Revenue remains one of the most important numbers in an SME. The answer is not to distrust a strong sales result or discount every exceptional order.
The answer is to understand the composition.
A business with RM10 million of sales generated from stable repeat customers, acceptable margins and sensible payment behaviour faces different decisions from one that reached the same figure through two temporary projects. Both may be successful. They simply should not be managed as though their revenue has the same characteristics.
Before increasing fixed costs, committing to a larger facility or announcing that a new level of growth has become permanent, break the number apart.
Ask what repeated, what was exceptional, what produced margin, what produced cash and what can actually be proved.
That is how an SME moves from celebrating growth to understanding it.